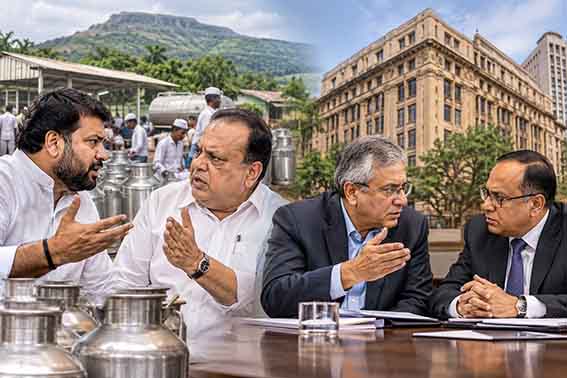
The elections to the Kolhapur Zilla Sahakari Dudh Utpadak Sangh Ltd (Gokul), and the sequence of events that followed, have attracted considerable media attention, largely because of the political contest underlying them. Yet the questions raised by the episode extend well beyond the immediate politics. Meanwhile, the affairs of Tata Sons have also been in the public gaze over the past few weeks. Despite being different entities with differing structures, certain parallels are unmistakable. Both episodes reveal the absence of clarity in the governance of institutions that occupy the space between conventional profit-making enterprises and organisations established to serve a wider public purpose.
Strictly speaking, neither Gokul nor Tata Sons, as presently constituted, is driven entirely by profit in the conventional sense. Gokul is a cooperative whose stated purpose is the collective welfare of its members. Tata Sons, although incorporated as a private limited company, is controlled by public charitable trusts. Both therefore operate within institutional arrangements in which the pursuit and distribution of economic value are shaped by objectives that extend beyond the immediate interests of shareholders.
At Gokul, the recent election produced an almost evenly divided verdict, with the winning panel securing thirteen seats against twelve for its rival. This has raised a practical question about the mandatory quorum of fourteen. If the two panels refuse to cooperate in electing a chairman, the board could find itself in a deadlock. To address this possibility, the Maharashtra government amended the relevant rules to permit the nomination of additional directors with voting rights. The consequence could be that a panel elected with thirteen seats finds itself reduced to a minority when it comes to selecting the chairman.
At Tata Sons, a disagreement between two Tata Trusts-nominated directors over a key decision was resolved by the chairman’s casting vote, although he is not a Trusts nominee. The situation has been further complicated by the Maharashtra Public Trusts Act amendment, effective September 1, 2025, capping perpetual trustees at 25 percent. On May 15, 2026, the Maharashtra Charity Commissioner issued an ex-parte order freezing routine board proceedings of the Sir Ratan Tata Trust, citing its violation of the new ceiling.
In both instances, the amended provisions apply to organisations crossing specified revenue thresholds. While the disputes are before the courts, the more fundamental issues concern the continuing relevance of cooperative institutions in a modern market economy and the precise boundary between the commercial objectives of a company and the public-interest obligations of the trusts controlling it.
Cooperatives Reconsidered
The cooperative movement emerged in an economic and social environment very different from the one India inhabits today. Private entrepreneurship was relatively scarce and weak, while the desire to earn profits was often regarded with suspicion. Pooling resources through voluntary membership and mutual cooperation provided a framework for pursuing common economic objectives while carrying an accompanying sense of social purpose and collective upliftment.
That historical context has changed considerably. Profit-driven enterprises and equity ownership are now widely accepted features of economic life. Whether in banking, dairy production or sugar manufacturing, institutions in the private, public and cooperative sectors operate in the same markets, compete for customers and must generate sufficient earnings to sustain themselves and reward their respective stakeholders.
Even the non-monetary benefits offered by cooperatives to their members are, directly or indirectly, dependent on their ability to generate sound financial returns. A dairy cooperative, for instance, cannot consistently secure better prices and services for its members if its underlying business is financially unsustainable.
There is, therefore, a strong case for asking why large cooperatives should not be subjected to governance and accountability standards comparable to those applicable to publicly listed companies. At present, many occupy an uncomfortable statutory middle ground. They neither discharge public obligations in the manner expected of public-sector institutions nor face the full discipline of market competition without special treatment from the government.
This neither-here-nor-there status can become fertile ground for inefficiency and malpractice. The experience of India’s cooperative banking sector illustrates the risks. Over the past fifteen years, around 100 cooperative banks have shut down or been forced into liquidation or merger because of bankruptcy, serious financial mismanagement or chronic capital inadequacy. The Reserve Bank of India has cancelled the licences of at least 78 urban cooperative banks since 2014. Maharashtra, historically one of the principal centres of the cooperative movement, accounts for roughly half of these cancellations.
The consequences have been borne disproportionately by ordinary depositors. Hundreds of thousands of account holders have seen their savings jeopardised, with thousands of crores of rupees affected in the collapse or failure of institutions such as PMC Bank, CKP Bank, Rupee Cooperative Bank and New India Cooperative Bank. The regulatory arrangements governing cooperative banks have historically differed from those applicable to conventional commercial banks, with oversight responsibilities distributed between the RBI and NABARD.
The larger question, therefore, is whether the institutional distinction between cooperatives and conventional companies continues to justify substantially different standards of governance when both operate in increasingly similar commercial environments.
Profits With Purpose
The Tata structure presents a different, though equally interesting, challenge. The individual companies within the Tata Group are conventional profit-seeking enterprises, many of them publicly listed. Tata Sons, their holding company, was established within a framework shaped by public charitable trusts, principally the Sir Dorabji Tata Trust (SDTT) and the Sir Ratan Tata Trust (SRTT). The underlying philosophy was that the wealth generated by commercial enterprise should ultimately serve society and contribute to nation-building.
Through their controlling stake, the Tata Trusts retain the prerogative to determine what would best advance these broader objectives. The charitable trusts are not-for-profit institutions, while the listed companies controlled by Tata Sons operate for profit. Tata Sons itself, however, occupies an intriguing position somewhere between these two worlds.
This institutional arrangement has also brought it under regulatory scrutiny. The RBI has classified Tata Sons as an Upper Layer Non-Banking Financial Company (NBFC) and, under its revised regulatory framework, requires it to become a publicly listed company.
Contradictions and Ambiguities
Unlike cooperative banks plagued by insolvency, inadequate capitalisation and governance failures, Tata Sons has remained financially sound, with an exemplary record of governance, philanthropy and nation-building. This raises the question of whether compelling it to go public is the most appropriate means of ensuring transparency and accountability. The irony is that thousands of cooperative banks continue to operate within a regulatory framework where the division of supervisory responsibilities between the RBI and NABARD has often left gaps. The contrast underscores the need for greater consistency in applying regulatory standards across institutions.
In Gokul’s case, it could be argued that, instead of changing the rules to nominate additional directors and thereby potentially overturning the effective majority produced by an election, the government could have considered adjusting the quorum requirement while respecting the popular verdict.
Similarly, instead of requiring Tata Sons to go public and potentially altering the distinctive trusteeship-based philosophy underpinning its ownership structure, the RBI could consider prescribing additional governance safeguards and accountability mechanisms for Upper Layer NBFCs without necessarily insisting on a public listing.
Several fundamental questions deserve serious consideration. Should an entity that decides how profits are to be deployed necessarily be profit-driven itself? Does the traditional cooperative model remain relevant in contemporary industrial sectors such as banking, dairy and sugar manufacturing? And if public listing is indeed the most effective way of ensuring transparency and accountability, why should that principle not be applied consistently across the board, including to large cooperative institutions?
What is needed is a contemporary, enabling statutory framework that recognises the diversity of institutional objectives while establishing clear and consistent standards of governance.
India’s regulatory framework must evolve accordingly. The challenge is not to choose between profit and public purpose, but to establish rules under which the two can coexist without contradiction.
(The writer has worked in the Information Technology sector. Views are personal)