top of page

By:

C.S. Krishnamurthy

21 June 2025 at 7:45:51 pm

Let Your SIP Fight Your EMI

When Ramesh bought his first home, he was delighted. The keys were finally in his hand, but another number immediately occupied his mind: the monthly EMI. “Now that I have some money left after paying my EMI, what should I do with it?” he asked his financial adviser. “Or should I start investing? And if I invest, won’t I be carrying a loan unnecessarily?” A home loan can run for 15, 20 or even 25 years, while the desire to become debt-free keeps growing. But does a borrower necessarily have...

Let Your SIP Fight Your EMI

When Ramesh bought his first home, he was delighted. The keys were finally in his hand, but another number immediately occupied his mind: the monthly EMI. “Now that I have some money left after paying my EMI, what should I do with it?” he asked his financial adviser. “Or should I start investing? And if I invest, won’t I be carrying a loan unnecessarily?” A home loan can run for 15, 20 or even 25 years, while the desire to become debt-free keeps growing. But does a borrower necessarily have to choose between repaying the loan faster and investing for the future? What if both could be pursued simultaneously? Could a Systematic Investment Plan (SIP) create a corpus that eventually helps reduce or even close the home loan? The idea merits consideration. A SIP is not a magic formula for becoming debt-free, but it can create a second financial track alongside the regular EMI. Two tracks, one objective Consider an illustration. Suppose a borrower takes a home loan of ₹50 lakh at an assumed interest rate of 8.5 pc for 20 years. The EMI would be around ₹43,400.
Instead of putting every available rupee into the loan, the borrower could consider investing ₹10,000 a month through a SIP, provided the household cash flow permits it. At an assumed annualised return of 12 pc, a ₹10,000 monthly SIP could grow to roughly ₹8.24 lakh in five years, ₹23.23 lakh in 10 years, ₹32.22 lakh in 12 years and ₹50.45 lakh in 15 years. While these are not guaranteed returns, the possibility of higher returns is also not ruled out. Meanwhile, the outstanding home loan would gradually decline through EMIs. Over eight to 10 years, the SIP corpus could become substantial enough to give the borrower an additional financial option. The important point is not to decide today exactly when the loan will be closed, but to review the position when the time comes. Why not simply prepay? Prepaying the home loan provides a relatively certain benefit because every rupee of principal repaid reduces future interest outgo, subject to the loan terms and applicable rules. The SIP serves a different purpose. It creates a financial asset and, over the long term, gives the investor an opportunity to participate in the growth potential of financial markets. The decision point comes later The strategy need not have a fixed finish line. After eight to 10 years, the borrower can review the situation rather than mechanically redeeming the SIP. What is the outstanding loan, the investment value and its performance? What are the prevailing market conditions? Is part-prepayment more appropriate than full repayment? These questions can guide the decision. If the corpus has grown sufficiently and circumstances are favourable, the borrower may consider using part of it to reduce the outstanding loan or, if appropriate, redeeming enough to close the loan completely. If the investment is better retained for the long term, there is no compulsion to exit merely because 10 years have passed. The strength of the strategy lies in this flexibility. Think beyond the loan A long-term SIP is not merely a future home-loan repayment fund. It can become a wealth-creation vehicle in its own right. Compounding rewards patience. A disciplined monthly investment held for the long term can help build a corpus for retirement, children’s education, other life goals or financial independence. Thus, while the home loan moves towards closure through the EMI, the investment has the opportunity to grow alongside it. Once the loan is eventually closed, the EMI disappears. Instead of allowing that money to quietly disappear into lifestyle expenses, the borrower can redirect some or all of the former EMI towards investments. A sensible balance This approach is not a universal prescription. Some borrowers may prefer aggressive loan prepayment, while others may find the combination of EMI and SIP more suitable. The SIP amount should also be comfortable. If ₹10,000 strains the monthly budget, start with less. The strategy should strengthen financial security, not create financial pressure. Adequate emergency savings and appropriate insurance should also form part of the overall financial plan. The larger lesson is simple: a home loan need not automatically put wealth creation on hold. With disciplined cash-flow management, a long-term investment approach and periodic reviews, the EMI can continue paying for today’s home while the SIP works towards tomorrow’s financial freedom. In the end, the question need not be, “Loan or investment?” It can be: “How can I use both wisely?” Disclaimer: “Mutual funds are subject to market risks. Read all scheme-related documents carefully.” (The writer is a retired banker and author. Views personal.)

Real estate the new gold for investment

May 15
3 min read

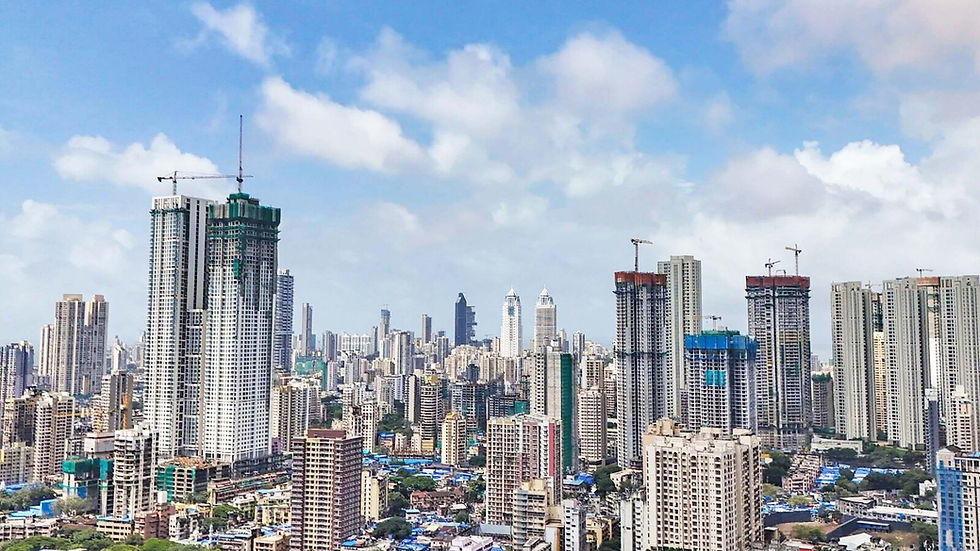
Mumbai: As India’s investment landscape evolves, a growing debate is emerging among investors over which asset class truly delivers superior long-term wealth creation — gold, stocks or land. While gold has historically served as a trusted safe-haven asset and equities have generated substantial wealth during economic booms, real estate-backed land investments are increasingly gaining prominence due to infrastructure expansion, urbanisation and long-term appreciation potential.


The discussion has gained additional relevance following Prime Minister Narendra Modi’s recent appeal urging citizens to reduce non-essential gold purchases to help conserve India’s foreign exchange reserves. The statement has sparked conversations across financial and investment circles about whether investors may increasingly shift focus towards equities and tangible real estate assets.


Traditionally, gold has been viewed as a reliable hedge during periods of economic uncertainty. It offers stability and liquidity, making it a preferred choice during volatile market conditions. However, experts point out that while gold preserves wealth, it may not always generate significant long-term appreciation compared to other growth-oriented assets.


Stocks, meanwhile, continue to remain one of the fastest wealth-generating avenues. India’s equity markets have produced substantial returns over the years, particularly for disciplined long-term investors. Yet, equities are also exposed to sharp market fluctuations, global uncertainties and cyclical corrections, making them suitable largely for investors with higher risk tolerance and active market participation.


In contrast, land investments are steadily emerging as a compelling long-term wealth creation strategy, particularly in rapidly developing growth corridors surrounding major cities. Improved connectivity, new highways, metro corridors, industrial zones and large-scale infrastructure projects are transforming peripheral regions into high-potential investment destinations.


Unnati Varma, Director, ORA Land (by ORA Group), said, “Gold and stocks will always remain important components of a diversified portfolio, but land investment has a unique long-term advantage because of its finite nature and growing demand. With major infrastructure projects opening up new growth corridors, strategically located land parcels are witnessing strong appreciation potential. Investors today are increasingly looking at land not only as an emotional asset but also as a high-growth investment opportunity with lower volatility over the long run.”


Biggest Advantage

Industry leaders believe the biggest advantage of land lies in its tangible and finite nature. Unlike stocks, which are market-linked, or gold, which is globally price-sensitive, land values are often directly influenced by infrastructure-led development and urban expansion.


Kamlesh Thakur, President, NAREDCO Maharashtra and Co-Founder & Managing Director, Srishti Group, said, “Every asset class plays a distinct role in an investor’s portfolio. Gold offers stability during periods of uncertainty, equities create opportunities for higher growth, while land continues to stand out as a resilient, inflation-resistant asset with strong long-term appreciation potential. In India, ownership of land and real estate also carries deep aspirational and generational significance, making it one of the most preferred investment avenues.”


He added, “A major catalyst driving land investments today is infrastructure-led urban expansion. Emerging highways, metro corridors, industrial hubs, and large-scale connectivity projects are transforming peripheral regions into high-potential investment destinations around major cities.”


Nihar Jayesh Thakkar, Founder, The Mandate House Pvt. Ltd., observed that investor preferences are gradually becoming more strategic and future-focused. “Stocks may deliver faster returns during bullish cycles, but they also demand higher risk tolerance and active monitoring. Gold acts more as a defensive asset. Land, particularly in high-potential growth corridors, offers a balanced proposition of long-term capital appreciation and asset security,” he said.


As India’s economic landscape expands beyond metropolitan cores into emerging corridors and Tier-II regions, experts believe land investments could play a defining role in the next phase of wealth creation. While financial planners continue to advocate diversification across asset classes, real estate, especially strategically located land parcels, is increasingly being viewed not merely as a traditional asset, but as a long-term engine of sustainable wealth generation. 

Comments


bottom of page