

The Price of Plenty

In India’s farm policy, arithmetic often collides with reality. Nowhere is this more evident than in Maharashtra, where the official logic of Minimum Support Prices (MSP) struggles to keep pace with the lived economics of cultivation. As the 2025–26 agricultural season unfolds, fresh evidence from the state’s Agricultural Price Commission suggests that the gap between what farmers spend and what they earn is widening.
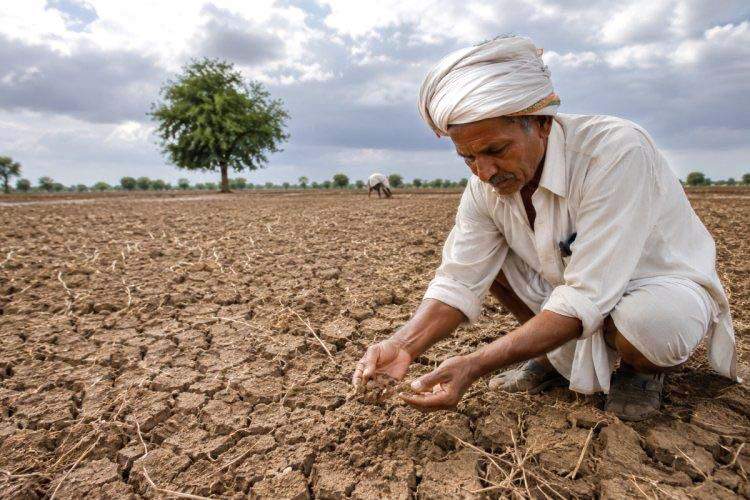
At first glance, Maharashtra appears an agricultural powerhouse. Its farms span roughly 165 lakh hectares, covering more than half the state’s land. But beneath this impressive expanse lies a structural fragility. Barely a fifth of this land enjoys assured irrigation. The rest depends on the caprices of the monsoon. In such a setting, farming is less a business than a gamble, with rainfall serving as both benefactor and executioner. The average landholding, a modest 1.34 hectares, offers little cushion against adversity. A delayed monsoon or a brief dry spell can swiftly transform anticipated profits into mounting debt.
Tightening Vice
Costs, meanwhile, are rising with disquieting speed. For the 2026–27 season, machinery rentals are projected to increase by nearly a fifth. Fertiliser prices have surged even more sharply. Diammonium phosphate (DAP) and muriate of potash (MOP), both essential inputs, now command prices of Rs. 27,000 and Rs. 34,000 per tonne respectively. Though urea remains subsidised, this offers only partial relief. Labour, transport and other ancillary expenses continue their steady ascent. The cumulative effect is a tightening vice, leaving farmers increasingly reliant on credit.
Against this backdrop, the MSP regime appears curiously detached. Designed to provide a safety net, MSP is calculated using the A2+FL formula, which accounts for paid-out costs and the imputed value of family labour. This framework, administered by the Commission for Agricultural Costs and Prices, has long served as the backbone of India’s price support system. Yet in regions like Maharashtra, where farming conditions are harsher and risks more pronounced, its limitations are becoming apparent.
The alternative, known as the C3 cost framework, offers a more expansive view. It incorporates not only direct expenses and family labour but also the rental value of land, interest on owned capital, managerial input and a notional profit margin. When MSP is evaluated against this broader measure, the inadequacy of current pricing becomes stark.
Consider paddy. For the 2025–26 season, Maharashtra’s calculations suggest a remunerative price of around Rs. 4,783 per quintal. The central MSP, however, stands at just Rs. 2,369 - barely half the estimated cost under the C3 framework. Similar disparities exist for other crops, including pearl millet (bajra), a staple of the state’s rainfed regions. They represent tangible income foregone, and, in many cases, the difference between viability and distress.
Such estimates are grounded in extensive fieldwork. Four of Maharashtra’s agricultural universities - located in Rahuri, Parbhani, Akola and Dapoli - collect data from nearly 2,800 farmers across diverse agro-climatic zones. Their findings capture the granular realities of cultivation: fluctuating input prices, regional variations in yield and the hidden costs that seldom find their way into official calculations. This evidence lends weight to the argument that a one-size-fits-all MSP is ill-suited to India’s heterogeneous agricultural landscape.
Raising MSPs to reflect C3 costs would undoubtedly improve farm incomes, but it also carries fiscal and market implications. Higher procurement prices could strain government budgets and distort cropping patterns. Yet ignoring the problem risks perpetuating a cycle of indebtedness and disinvestment in agriculture.
Reducing Costs
One promising avenue lies not only in recalibrating prices but also in reducing costs. Maharashtra’s push towards natural farming is instructive in this regard. By minimising reliance on chemical fertilisers and external inputs, such practices can lower expenditure while enhancing soil health. For rainfed areas, where irrigation constraints already limit productivity, this approach offers a measure of resilience. It shields farmers, to some extent, from the volatility of global input markets and the vagaries of supply chains.
Still, cost reduction alone cannot bridge the gap. What is required is a more nuanced MSP framework that accounts for regional disparities, incorporates a fuller spectrum of costs and remains responsive to changing economic conditions. This need not entail a wholesale abandonment of the existing system but a shift from uniformity to flexibility, from abstraction to empiricism.
Ultimately, the debate over MSP is not merely about numbers. It is about the social contract between the state and its farmers. Ensuring that farmers receive prices commensurate with their costs is not simply an economic imperative; it is a moral one.
(The writer is a member of Maharashtra Agriculture Price Commission. Views personal.)


Comments